Stressed
by Debt?
Let’s Talk.
Collection calls, lawsuits, wage garnishments, foreclosures: there may be a way to stop them. Tell us what you’re facing. We’ll explain your options in plain English, with no judgment and no pressure.
Every Kind of Debt.
Every Kind of Income.
Medical bills, credit cards, tax debt, even student loans — we know how each is treated in bankruptcy, and we use our deep knowledge of the Bankruptcy Code to make the most of the protections it offers you. Whether you earn $30,000 or $300,000 a year, we can help you find a way out of debt.
WHAT WE HELP WITH
How bankruptcy can give you a fresh start
-
Consumer bankruptcy is a legal process that helps individuals overwhelmed by debt get a real fresh start. The moment you file, a powerful federal protection called the automatic stay takes effect. It immediately halts most collection efforts — creditor calls, lawsuits, wage garnishments, foreclosures, and repossessions — giving you room to breathe while your case moves forward. For many people, it’s the first relief they’ve felt in months or years.
-
Often called a “fresh start” bankruptcy, Chapter 7 eliminates most unsecured debts — credit cards, medical bills, and personal loans — typically in just a few months. It’s designed for people with limited income who qualify under a means test. Most filers keep their essential property through exemptions and come out the other side debt-free.
-
Chapter 13 lets you keep your property while repaying some or all of your debt through an affordable plan that lasts three to five years, based on your income. It’s a strong option if you’re behind on a mortgage or car loan and want to catch up, or if you earn too much to qualify for Chapter 7. When the plan is complete, remaining eligible balances are discharged.
-
Chapter 11 is a reorganization option for individuals whose debts are too high to fit within Chapter 13’s limits, or whose finances are too complex for Chapter 7. It lets you restructure what you owe and keep valuable assets while you continue to earn. Though best known as a tool for businesses, it can be a genuine lifeline for high-income or high-debt individuals who need a manageable path forward.
-
Usually not. New York’s exemptions protect a significant amount of home equity and vehicle value, and Chapter 13 lets you catch up on missed payments over time. How much is protected depends on your equity and where you live.
-
In most cases, yes. The moment you file, a court order called the automatic stay generally halts wage garnishments, collection lawsuits, foreclosure sales, and collection calls. A few debts, such as child support, are treated differently.
-
Not necessarily. Chapter 7 uses a means test that looks at your income and your expenses, not just your salary. If you don’t qualify, Chapter 13 or Chapter 11 may still be available, including for higher earners.
-
A Chapter 7 can stay on your credit report for up to 10 years; a Chapter 13 is typically removed after 7. Many people begin rebuilding credit soon after their case ends, especially if they were already behind on payments.
General information, not legal advice. Every situation is different.
Hi, I’m Jonathan
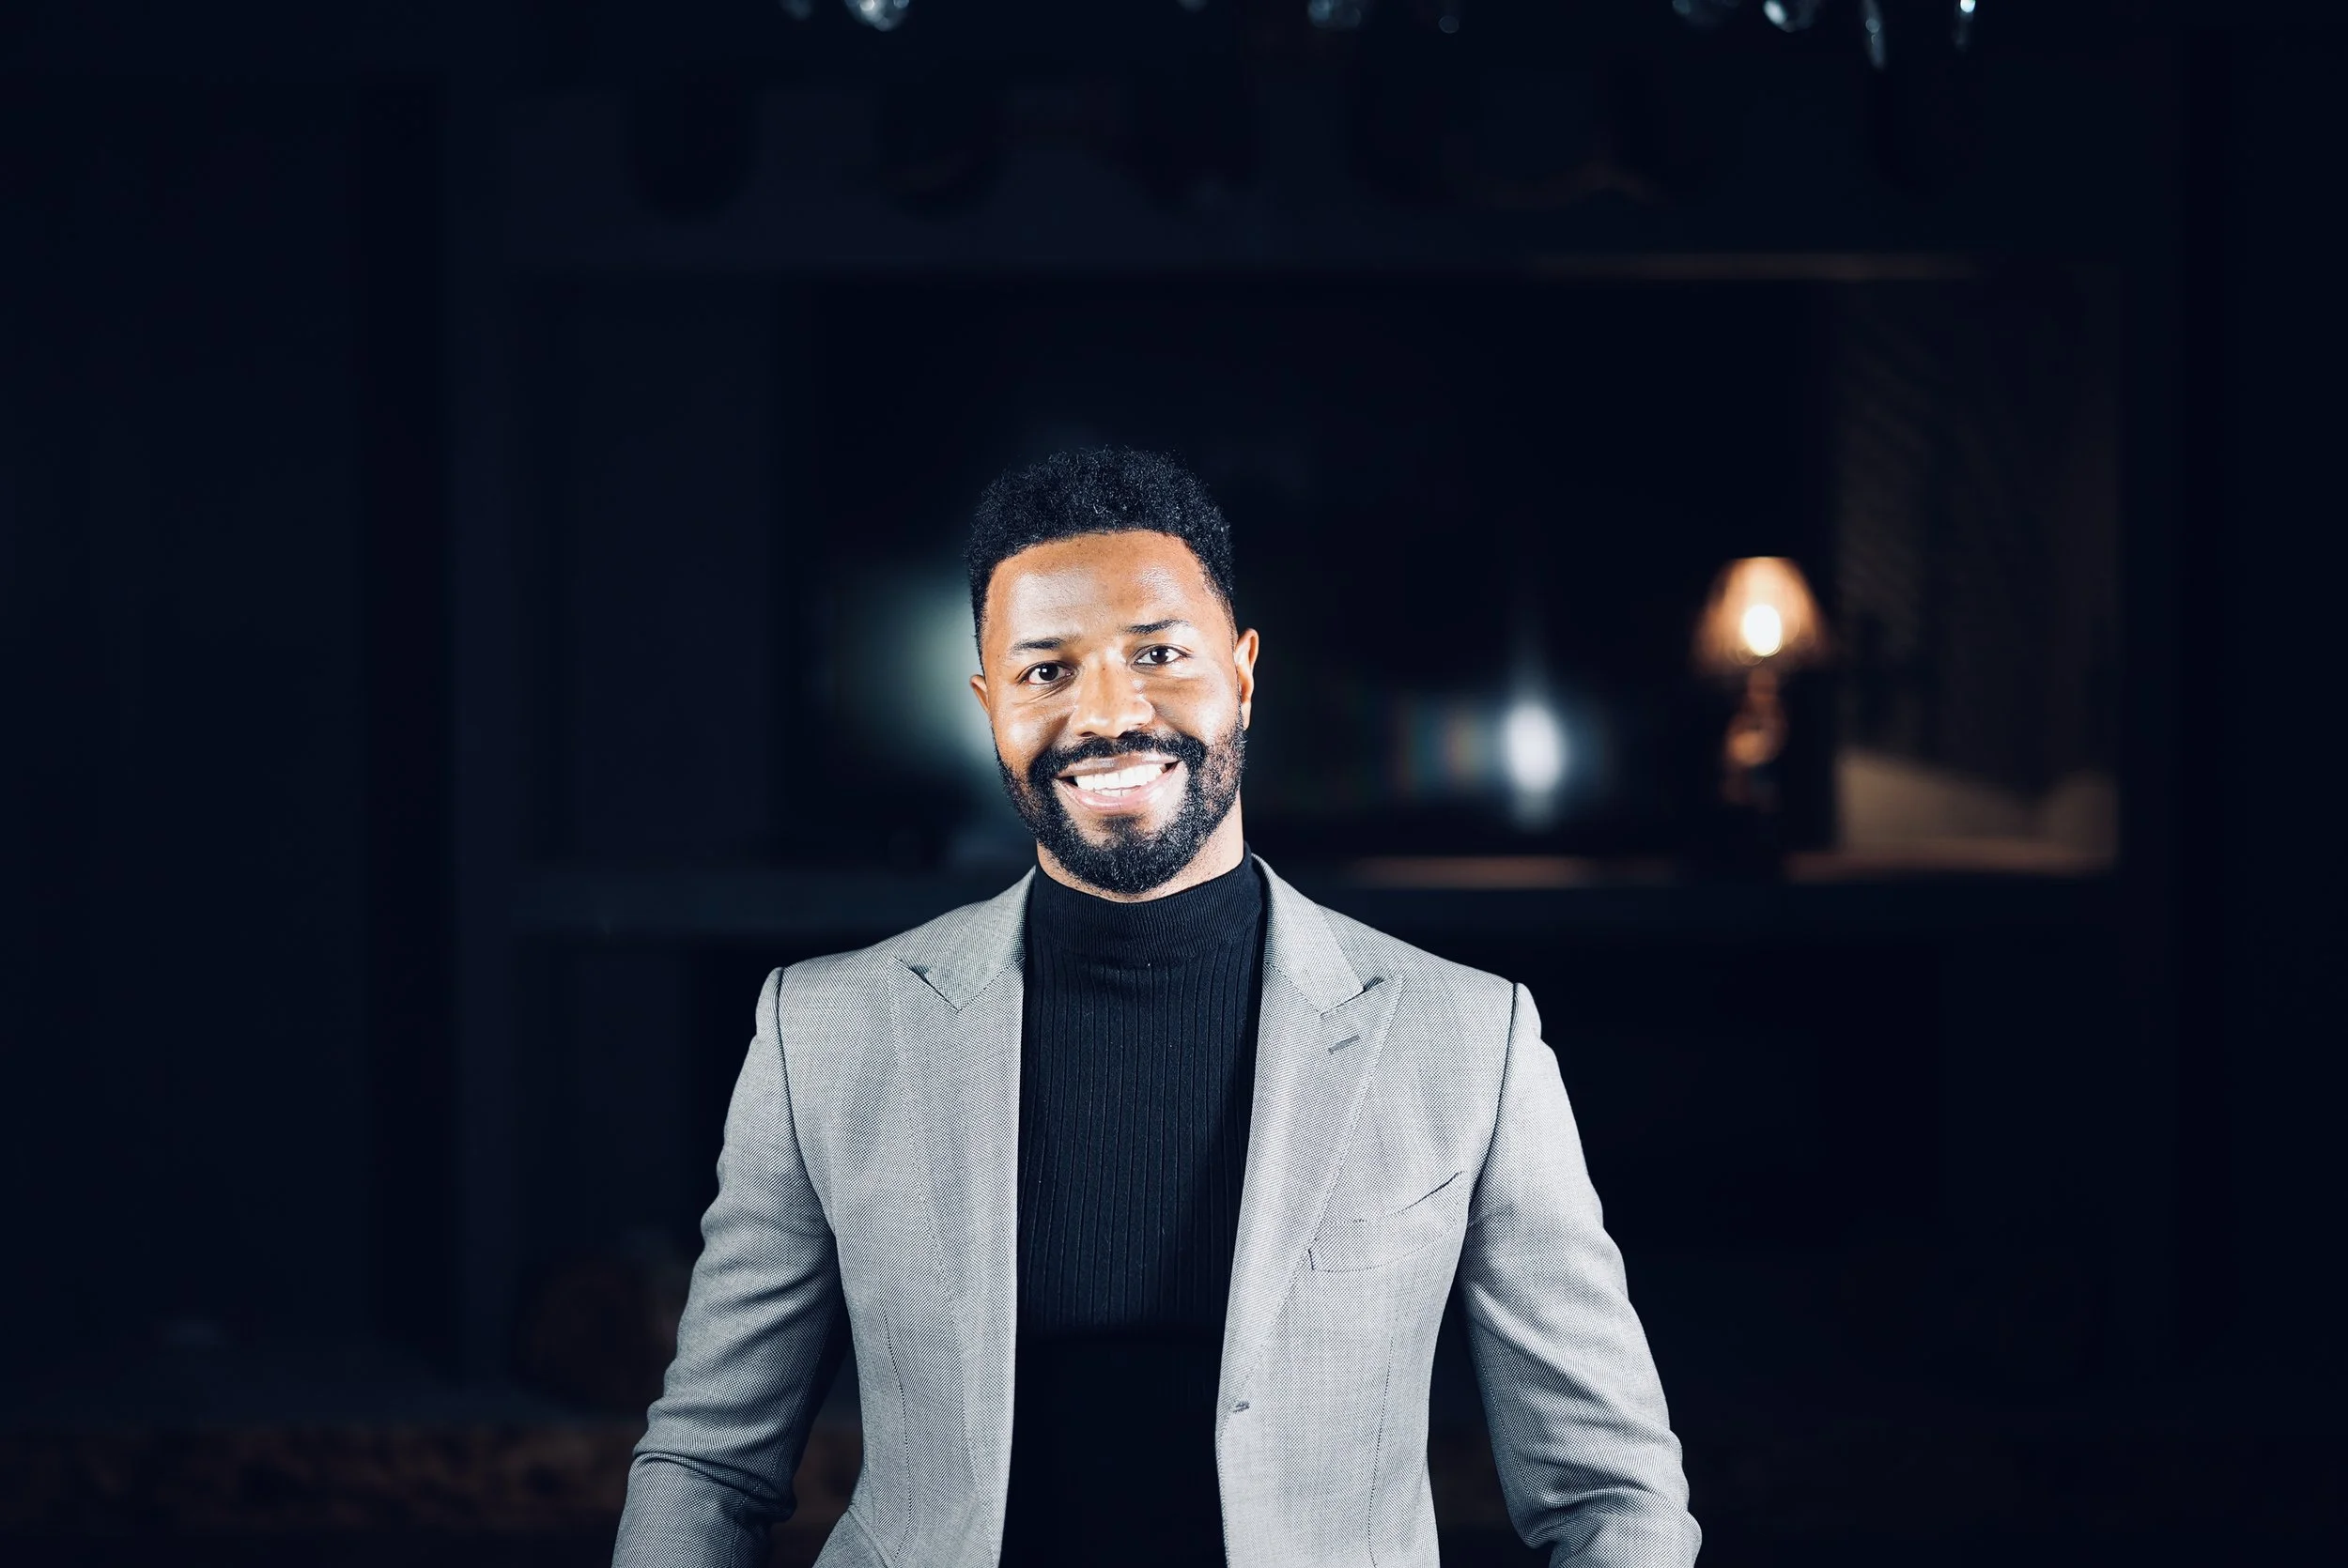
I started my career as a public defender/criminal defense attorney, where I represented people at risk of losing their liberty. That work developed within me the confidence, skill and ability to navigate people through high-stakes situations.
During this work, I noticed the inextricable link between lack of economic opportunity and involvement with the criminal legal system. The harsh reality is that those with means are able to afford better representation.
I often represented people who lost their homes, cars and wages because they could not afford adequate representation. Economic Justice, I saw, was as important as Criminal Justice.
One day, I read about the debt jubilees described in the Hebrew Bible—times when debts were forgiven, slaves freed, and land returned to families. These weren't simply moral gestures; they were ways to keep society from collapsing under the weight of unpayable debt.
I later discovered that this tradition went back even further, to the ancient Near East, where kings would declare clean slates to restore economic balance and allow ordinary people to begin again. Throughout history, societies have recognized that debt tends to grow faster than anyone can repay. Without periodic forgiveness, freedom itself erodes.
That's why bankruptcy law fascinates me. It's our modern version of a debt jubilee—a legal and humane way to reset, rebuild, and start over. My practice exists to help people do just that: reclaim stability, restore dignity, and move forward.
EDUCATION
Penn State University
Fordham Law
ADMISSIONS
New York State
U.S. District Court, S.D.N.Y.
U.S. District Court, E.D.N.Y.